Find out what your company's 401(k) really costs, and how it compares. Complimentary benchmarking, plan advisor searches, and request for proposal (RFP) support from a Qualified Plan Financial Consultant (QPFC).
401(k) Benchmarking & Plan Reviews for Orange County Companies
A 401(k)'s costs are spread across recordkeeping, administration, fund expenses, and advisory fees, so the total is hard to see. A benchmark review puts it all in one place and compares it with plans of similar size.
Get a complimentary benchmark review
Serving companies throughout Orange County.
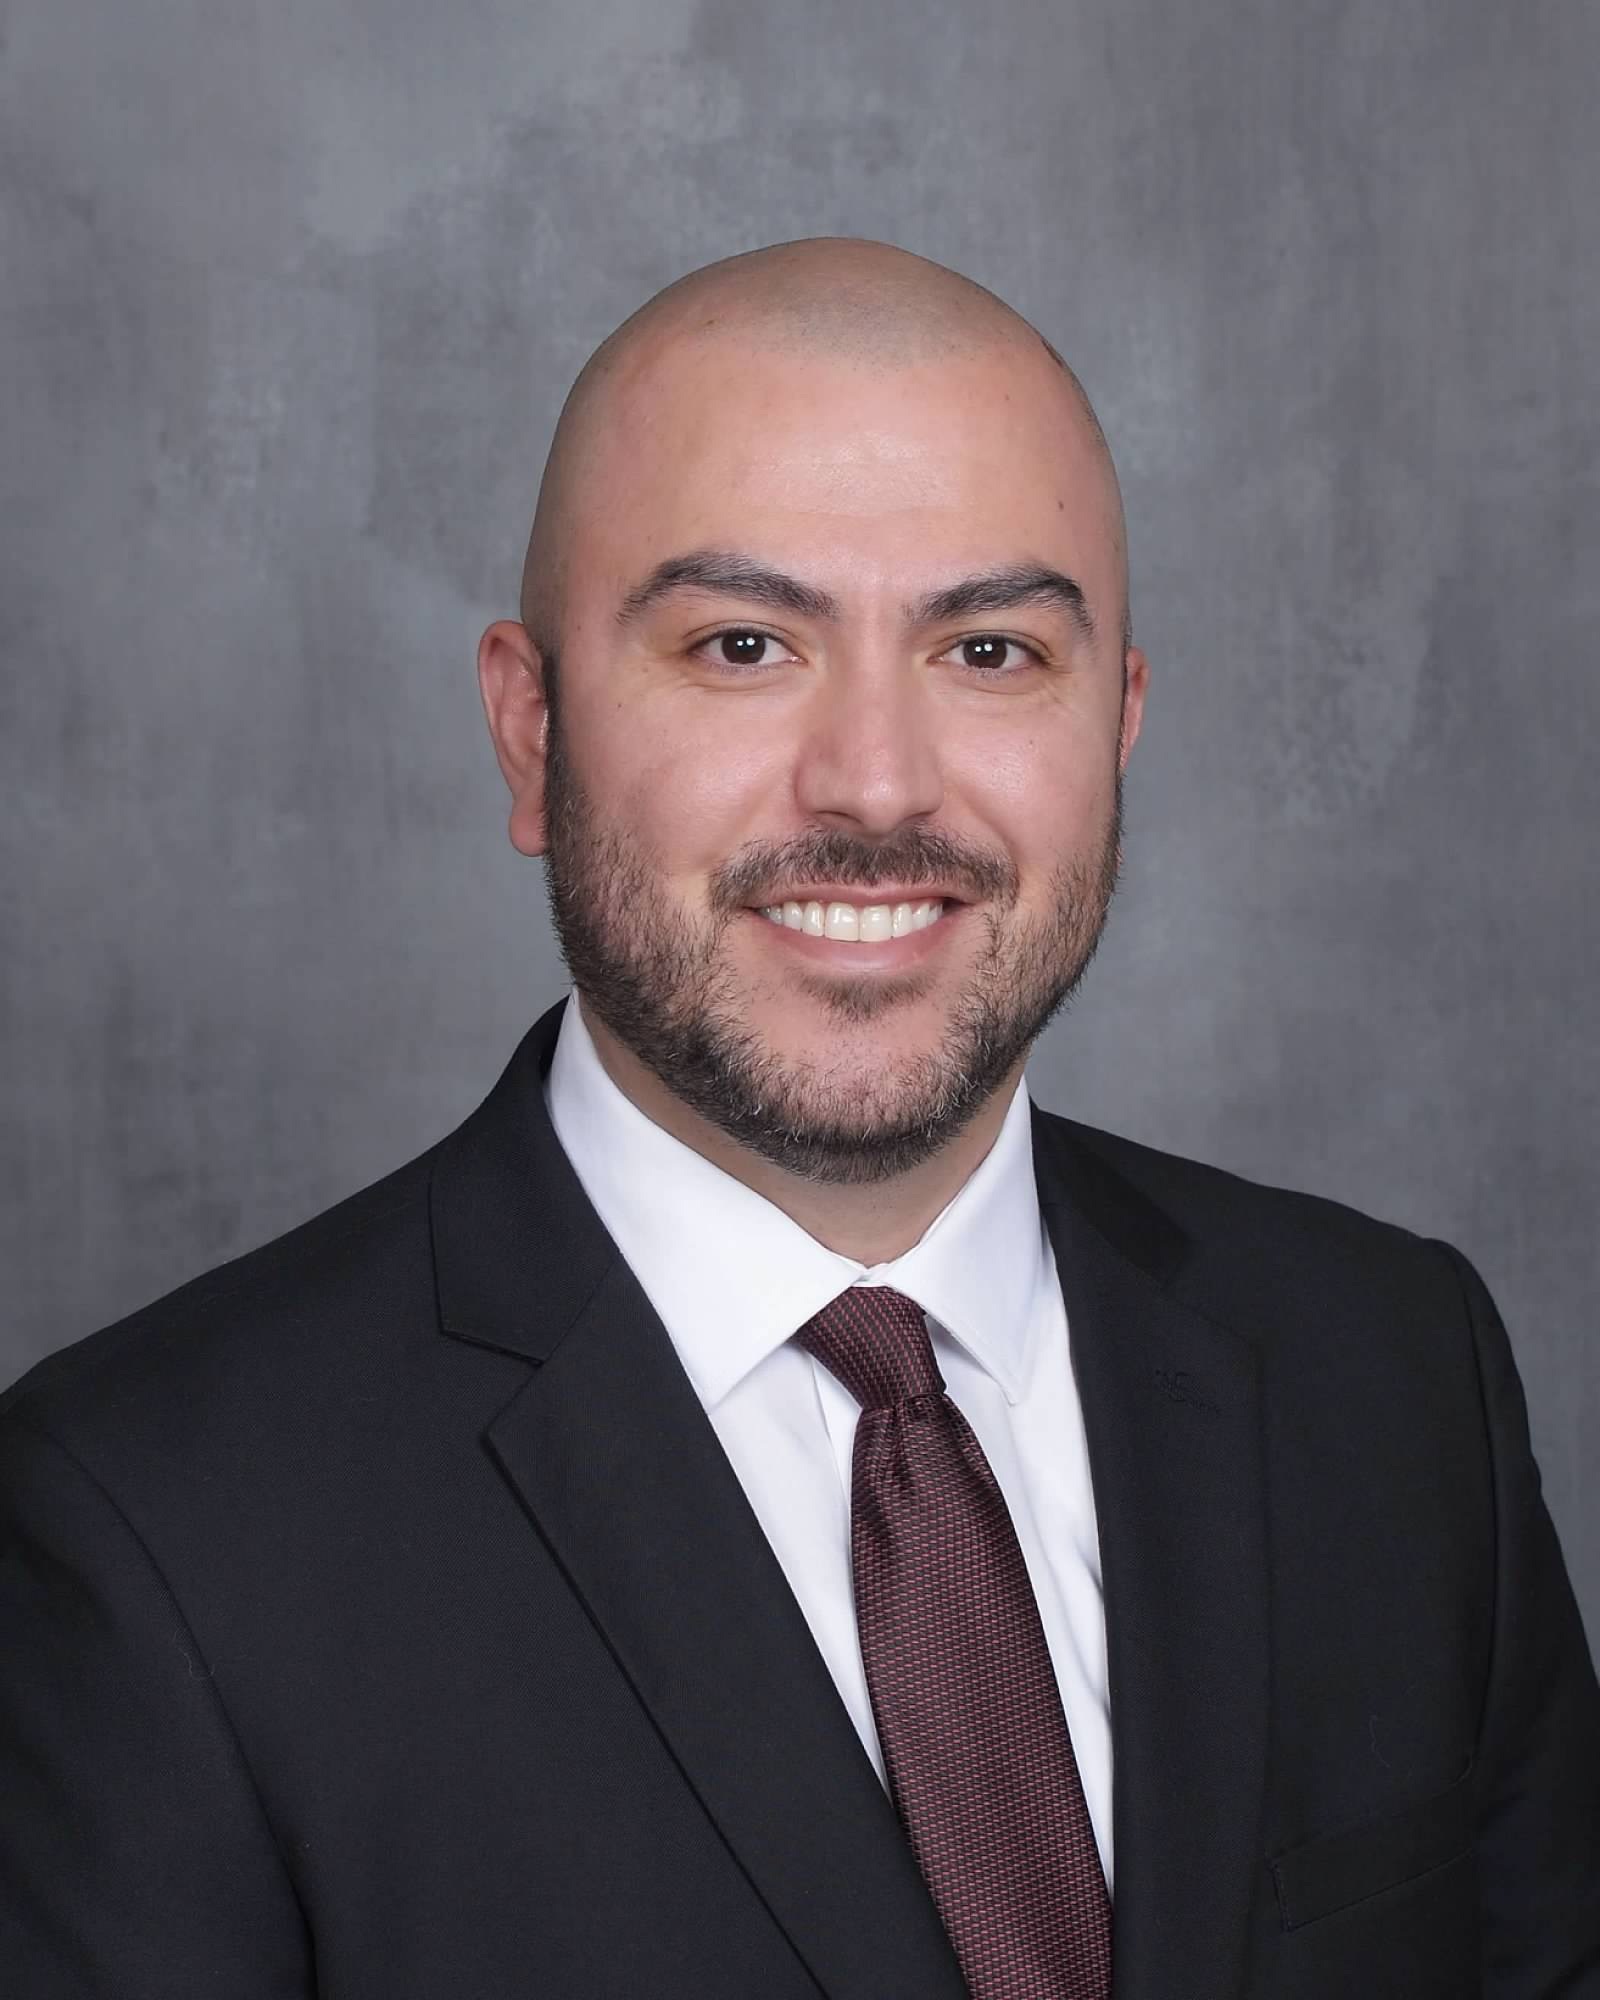
Your complimentary benchmark review
- ✓No cost, and no obligation to change anything
- ✓A written benchmark report you keep
- ✓You decide what, if anything, happens next
QPFC
Qualified Plan Financial Consultant
Any provider
ADP, Empower, Fidelity, and more
Committee-ready
Findings you can present to your plan committee
Why plan sponsors benchmark their 401(k)
Fees are a fiduciary issue
Under ERISA, the people responsible for a plan must make sure its fees are reasonable for the services provided. Periodic benchmarking is how many sponsors document that.
Costs are spread out
Recordkeeping, administration, fund expenses, and advisory fees often show up in different places — and some never appear on an invoice.
Plans drift
A lineup, price, and design that fit five years ago may not fit a company that has grown since.
The benchmark review
What a 401(k) benchmark review covers
For plans on any recordkeeper — ADP, Empower, Fidelity, John Hancock, Nationwide, Paychex, Principal, Transamerica, Vanguard, Voya, and others.
Fees
Total plan cost, broken out — recordkeeping, administration, fund expenses, and advisory fees — compared with plans of similar size.
408(b)(2) disclosure · Revenue sharing · Per-participant cost
Investments
Fund expenses, share classes, and performance against peer categories — including your target-date series and default investment.
Expense ratios · Share classes · Default investment
Plan design
Match formula, auto-enrollment, safe harbor status, Roth options, and whether owners are getting full use of the plan.
Safe harbor · Auto-features · Owner savings
Fiduciary process
Whether there's an investment policy statement, a record of committee reviews, and a documented review cycle.
Investment policy statement · Committee minutes · Review cadence
Want this for your plan? Get a complimentary benchmark review →
What you receive
A clear, written report you keep
A written benchmark of your plan against industry data for plans of similar size, a short list of items worth a closer look, and questions you can take to your current provider.
Sample layout — illustrative only, not actual plan data.
Want to see how your plan compares?
Get a complimentary benchmark reviewWhy a QPFC
Why a Qualified Plan Financial Consultant matters for your 401(k)
Under ERISA, the people who run a 401(k) must act prudently and solely in the interest of participants. They also need to keep fees reasonable and document how each decision was made. The QPFC credential from the National Association of Plan Advisors (NAPA) is built around that work.
Fiduciary roles under ERISA
Who is a fiduciary for your plan, what ERISA's prudence and exclusive-purpose rules require, and how 3(16), 3(21), and 3(38) roles divide the work.
Reasonable fees
What each provider is paid, including revenue sharing and conflicts of interest, so your committee can show fees are reasonable for the services received.
Investment policy and reviewing
Writing and keeping an investment policy statement, reviewing the lineup on a set schedule, and documenting when and why a fund is replaced.
Committee governance
Running committee meetings, keeping minutes and a fiduciary file, and training committee members on their duties.
Provider searches and conversions
A prudent process for choosing recordkeepers and advisors, comparing bundled and unbundled models, and documenting a provider change.
Participant outcomes
Plan design, automatic features, re-enrollment, and gap analysis to help improve employees' retirement readiness.
Built for plans with a committee
As a plan grows, so does the work: more participants and assets, a larger investment menu, often a formal committee, and more attention on fees. That is the process the QPFC exam covers.
Earned and kept
Earned by passing a proctored exam. Kept through annual continuing education, including ethics, and NAPA's Code of Professional Conduct. Verify it on NAPA Credential Check.
See how your plan's process compares. Get a complimentary benchmark review →
Advisor searches & RFPs
Changing advisors or providers?
Searching for a plan advisor
If your plan doesn't have an advisor, or yours hasn't reviewed the plan with you in a while, I'll walk you through how I'd support your plan, your committee, and your employees — and how I'm paid.
Running a recordkeeper or advisor RFP
Send your RFP and I'll respond on your timeline. If you're reviewing recordkeepers, I can help you define requirements, compare proposals side by side, and document the decision.
A review is a good fit if…
- ✓Your plan is established and growing — typically $1 million or more in assets
- ✓Your plan hasn't been benchmarked in the last three years — or ever
- ✓You're not sure what the plan costs in total, or who is paid what
- ✓Your company has grown, but the plan design hasn't changed
- ✓Owners or key employees want to save more than the 401(k) limit allows
- ✓You're a plan fiduciary and want a documented, outside review
Plan committees
Built for established plans
Reviews are designed for established company plans and the committees that oversee them. I can walk your committee through the findings, and the written report can go in your plan's fiduciary file.
How it works
Four steps, from request to report
01
Request
Leave your name and number in the form below. It takes under a minute.
02
Intro call
A short call to understand your plan and goals. I'll tell you which documents help — usually your annual fee disclosure.
03
Benchmark
I compare your plan with plans of similar size and prepare a written report.
04
Review & decide
We walk through the findings together. You decide what, if anything, to do next.
Step one takes under a minute. Request your review →
About
Sammy Khalil, QPFC
Financial Advisor · Wells Fargo Advisors
I'm a Financial Advisor and Qualified Plan Financial Consultant based in Orange County, focused on company retirement plans — 401(k)s, and cash balance plans for owners who want to save more.
Before becoming an advisor, I spent years working closely with business owners, which is what led me to this work.
I work with business owners, CFOs, HR leaders, and plan committees throughout Orange County.
You can verify my QPFC through NAPA Credential Check and my registration on FINRA BrokerCheck.
Ready to see how your plan compares? Get a complimentary benchmark review →
Start here
Get a complimentary benchmark review
Leave your name and number, and I'll call to learn about your plan. Everything else is optional and helps me prepare.
By submitting this request, you agree that the information you provide may be used by one of our associates from Wells Fargo Advisors to contact you about Wells Fargo Advisors' investment products and services. In addition, if you have other Wells Fargo products or services, you agree that Wells Fargo Advisors may share this information with those other Wells Fargo businesses or entities. Please review our privacy policy.
Questions Orange County business owners and CFOs ask about their company 401(k)
Tap a question to see the answer.
What is a QPFC, and why does it matter for our 401(k)?
A Qualified Plan Financial Consultant (QPFC) has passed NAPA's proctored exam on ERISA fiduciary practice: fiduciary roles, fee reasonableness, investment policy and reviewing, committee governance, and provider selection. Keeping the credential requires annual continuing education, including ethics. For a plan committee, it means working with an advisor trained in the process ERISA expects you to follow and document.
How do I know if our company's 401(k) fees are too high?
Start with your plan's annual fee disclosure (the 408(b)(2) notice), which shows what each provider is paid. Then compare the all-in cost with plans of similar size. That side-by-side comparison is exactly what a benchmark review gives you.
Does our company need a 401(k) advisor?
It isn't legally required. But the people who run a 401(k) are fiduciaries, responsible for prudent investment choices and reasonable fees. Many companies use an advisor to help select and review investments, benchmark costs, and document their decisions.
Can we switch 401(k) providers or advisors?
Yes. Companies change recordkeepers and advisors regularly. It takes planning — usually a search or RFP, a transition timeline, and advance notice to employees before any blackout period. A benchmark is often the first step to see whether a change is worth making.
How often should a 401(k) plan be benchmarked?
There's no fixed legal schedule. Many plan sponsors benchmark every few years, and again when something changes — the company grows, the plan's assets cross a new size band, or you're considering a new provider or advisor.
Can you review a plan with ADP, Empower, Fidelity, Principal, or Paychex?
Yes. A benchmark review works with any recordkeeper, including ADP, Empower, Fidelity, John Hancock, Nationwide, Paychex, Principal, Transamerica, Vanguard, and Voya.
Why is there no cost for the review?
Because some companies that go through it decide to work with me afterward. Many don't, and that's fine — you keep the report either way.
Will you contact my current provider or advisor?
No. The review stays between us unless you ask me to reach out.
What do I need to send?
Nothing to start — we begin with a conversation. If a benchmark makes sense, your annual fee disclosure (the 408(b)(2) notice) and a recent plan statement are usually all I need. Your plan's public Form 5500 filing also works as a starting point.
Can you respond to our RFP?
Yes. Check “RFP or recordkeeper search” on the form above, and I'll follow up for the RFP and your deadline.
Do you work with smaller plans?
My benchmark reviews focus on plans with $1 million or more in assets. If your plan is smaller, reach out anyway and I'll point you in a useful direction.
How quickly can we meet?
Request a call and I'll reach out to set up a time that works for you. No documents are needed to get started — we'll talk through your plan and what you're looking for, and go from there.
Is my information kept confidential?
Your information is handled under the Wells Fargo Advisors privacy policy.
For owners and executives
Know where your plan stands.
Complimentary 401(k) benchmark reviews for Orange County companies — no cost, no obligation.
Serving companies throughout Orange County
See every Orange County city I serve
- Aliso Viejo
- Anaheim
- Brea
- Buena Park
- Costa Mesa
- Cypress
- Dana Point
- Fountain Valley
- Fullerton
- Garden Grove
- Huntington Beach
- Irvine
- La Habra
- La Palma
- Laguna Beach
- Laguna Hills
- Laguna Niguel
- Laguna Woods
- Lake Forest
- Los Alamitos
- Mission Viejo
- Newport Beach
- Orange
- Placentia
- Rancho Santa Margarita
- San Clemente
- San Juan Capistrano
- Santa Ana
- Seal Beach
- Stanton
- Tustin
- Villa Park
- Westminster
- Yorba Linda
Plus unincorporated communities including Coto de Caza, Ladera Ranch, Midway City, Rossmoor, and Trabuco Canyon.
Important information
This information is for general educational purposes only. It is not a recommendation or individualized investment, tax, or legal advice.
Benchmark reviews compare your plan with third-party industry data for plans of similar size. That data is believed to be reliable but is not guaranteed to be accurate or complete.
The sample report is illustrative only and does not reflect any actual plan.
Information about ERISA and plan fiduciary responsibilities is general and is not legal advice. Plan sponsors should consult their ERISA counsel.
Initial reviews and consultations are offered at no cost and with no obligation. If you decide to open an account or use advisory services, applicable fees and expenses will be explained to you in advance.
The Qualified Plan Financial Consultant (QPFC) credential is awarded by the National Association of Plan Advisors (NAPA) and requires passing a proctored exam, agreeing to NAPA's Code of Professional Conduct, and completing annual continuing education. Holding the QPFC does not by itself make an advisor a fiduciary to a retirement plan. Whether Wells Fargo Advisors serves a plan in a fiduciary capacity depends on the services and agreement selected.
Links to third-party websites are provided for your convenience. Wells Fargo Advisors is not responsible for the content of those websites.